Filing the Delaware Annual Report (Corporations) and Paying the LLC Tax
Only corporations file a Delaware annual report: the Annual Franchise Tax Report, due March 1 and filed online with the Delaware Division of Corporations, part of the Delaware Secretary of State’s office. A Delaware LLC, LP or GP files no report; it pays a flat annual tax, $400 for tax year 2026, due June 1, 2027 (the June 1, 2026 payment was still $300).
Delaware annual report and tax calculator
Annual Franchise Tax Report Filing on DCIS eCorp
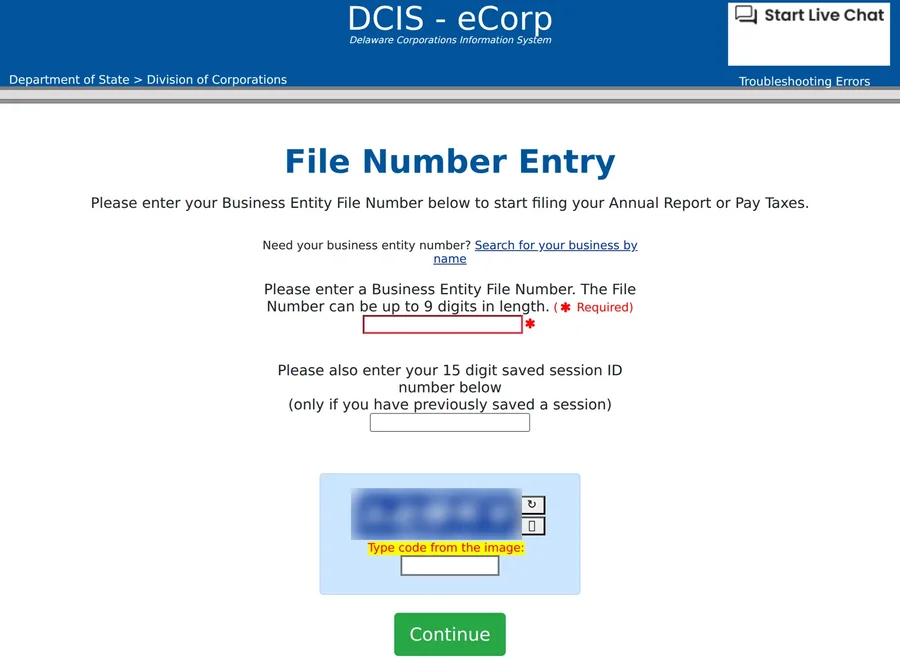
Domestic corporations, C corps and S corps alike, file the Annual Franchise Tax Report online only, on the Division of Corporations’ DCIS eCorp portal, by March 1, between 8:00 am and 11:45 pm Eastern Time. There is no paper form to download and no account to create: the report is the screen that opens with the company’s file number. Filing help: 302-739-3073, option 3.
- Find the file number. It has up to 9 digits; a Delaware business entity search shows it next to the company name.
- Open “File Number Entry”. Type the Business Entity File Number and the code from the image. A 15-digit saved session ID reopens a report started earlier, for two weeks.
- Check what the State already has, then complete the rest. Under 8 Del. C. § 502, the annual report requirements are the nature of the business, the principal place of business (never the registered agent’s address), the names and addresses of all directors, and the officer who signs: the president, secretary, treasurer or another proper officer, or a director. A knowingly false statement is perjury.
- Enter issued shares and total gross assets. Without them, the State bills the Authorized Shares method, which runs far higher when a company has many low-par shares.
- Pay, then press “Submit Filing”. Card, or ACH debit, which is required above $5,000. A saved session is not a filing: the report counts as filed once it is submitted and paid, and the acknowledgement copy can be viewed right away or emailed.
A foreign corporation files its report by June 30 with a $250 fee, and after two years without one it can no longer do business in Delaware; an exempt nonprofit corporation files by March 1 for $25, with no franchise tax.
Copies of filed annual reports can be ordered ($10 plain, $50 certified, plus $2 a page); the tax information in reports filed after tax year 2006 is not public.
The genuine franchise tax notice reaches the registered agent in December. The Division asks companies to treat as suspicious any tax or annual report letter that does not come from the State or from their Delaware registered agent; it names one solicitation, “Corporate Records Service”, which asks $125 to prepare meeting minutes.
Delaware Franchise Tax: Two Methods, You Pay the Lower One
The December notice uses the Authorized Shares method. A corporation with many authorized shares at a tiny par value can owe far less under the Assumed Par Value Capital method, but only if the annual report lists its issued shares and total gross assets.
Authorized Shares method
$175 up to 5,000 shares, $250 up to 10,000, then $85 per additional 10,000 shares or part of them. Maximum $200,000.
Assumed Par Value Capital method
- Divide total gross assets (Form 1120, Schedule L) by issued shares: that is the assumed par.
- Multiply the authorized shares by the assumed par, or by their own par value when it is higher.
- Pay $400 per million of that total, rounded up above $1 million. Minimum $400, maximum $200,000.
The Division’s franchise tax calculation page walks through the same steps.
Corporations with no-par stock always pay less under the Authorized Shares method. A listed corporation whose SEC filings show $750 million or more in revenue or assets (and at least $250 million of both) pays $250,000 instead of the $200,000 cap, as a Large Corporate Filer. When the prior year’s tax was $5,000 or more, the corporation pays estimates: 40% on June 1, 20% on September 1, 20% on December 1, and the rest with the report on March 1.
A corporation that did no business during the year pays half the rate for that period, and one formed during the year pays for the part of the year it existed.
Does a Delaware LLC Need to File an Annual Report?
No. Delaware sets no reporting requirements for LLCs: an LLC files no report, lists no members or managers, and pays the annual LLC tax for the calendar year that just ended by June 1.
LPs, and GPs that filed a statement of partnership existence, owe the same $400 under House Bill 400, signed May 21, 2026, and pay it by the same June 1 date.
There is no proration: an LLC formed on December 20 owes the full $400 for that year. The Division mails the tax statement to the registered agent at least 60 days before June 1. An LLC that closes pays the current year’s tax in full before its certificate of cancellation is filed.
In Delaware, renewal of an LLC is simply that June 1 payment: under 6 Del. C. § 18-1107(i), good standing holds as long as each year’s tax, with any penalty and interest, has been paid. The annual cost owed to the State is $400 per LLC and $100 per registered series, plus the $200 penalty and interest only when a payment is late.
“LLCs, LPs, and GPs are not required to file Annual Franchise Tax reports with the Division of Corporations, they must pay the $400 yearly tax on or before June 1st.”
Division of Corporations, tax instructions for LLCs, LPs and GPs
Void Charter or Canceled Certificate: Missing March 1 or June 1
Late payment adds a $200 penalty and 1.5% interest per month on the tax and penalty, for corporations and LLCs alike. Good standing ends the day after the due date.
Corporation
- March 2Good standing lost, $200 added, interest starts
- By November 30The Division sends a notice that the charter will become void
- Next March 1Charter void if still unpaid (8 Del. C. § 510)
- Revival$189 + back taxes, penalties and interest. Void more than 5 years: 3 times the current year's tax instead of the arrears
LLC, LP
- June 2Good standing lost, $200 added, interest starts
- Foreign LLCRegistration in Delaware ends as soon as the tax is missed
- Third anniversary of the due dateCertificate of formation canceled (6 Del. C. § 18-1108)
- Revival$220 + the taxes, penalties and interest due at cancellation
The Division’s online status costs $10, or $20 with tax and history, and is not a certificate; a short-form certificate of status is $50, a long-form certificate of good standing $175.